The ₱20 Daily Savings Challenge: Micro-Saving Habits for Long-Term Wealth
Master financial discipline without feeling the pinch. Explore our complete guide to the ₱20 daily savings challenge tailored for Filipinos.
Turn Your Loose Change into Real Wealth with the ₱20 Daily Challenge
Building strong financial security can feel like an overwhelming task when you are managing everyday living expenses in the Philippines. Between rising costs for public transportation, groceries, and utility bills, setting aside a large sum of money each month often feels nearly impossible. Many hard-working Filipinos delay starting their savings journey because they believe saving money requires thousands of pesos right out of the gate. 💰
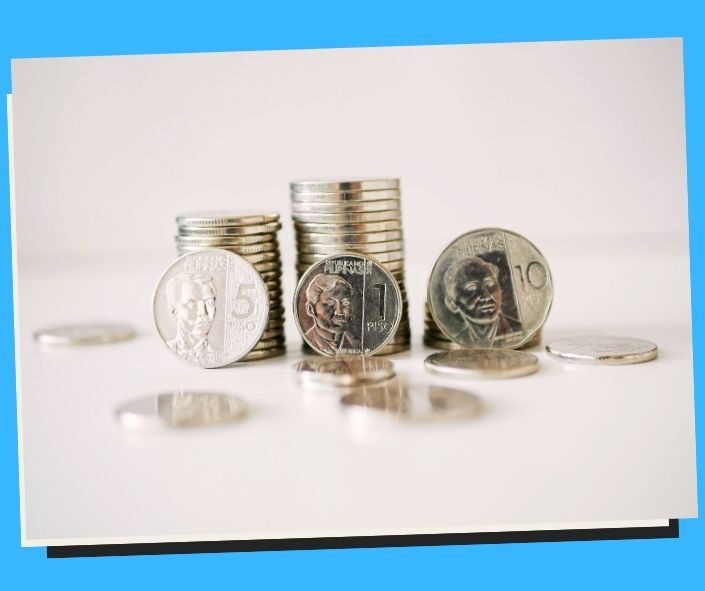
The truth is that sustainable financial growth does not start with massive deposits. It begins with small, consistent habits that compound over time. The ₱20 Daily Savings Challenge is a realistic micro-saving method designed specifically to help you build solid money management habits without straining your daily household budget. Setting aside just twenty pesos every single day allows you to accumulate over ₱7,300 in a year. This article walks you through the exact steps, tools, real-world examples, and strategies you need to master the ₱20 challenge and reach your personal finance goals.
How to Do the ₱20 Daily Savings Challenge in the Philippines
Executing this challenge successfully requires a structured plan rather than relying on pure willpower. Following a clear routine ensures that your daily savings remain consistent throughout the year.
+-----------------------------------------------------------------------------------+
| THE ₱20 DAILY SAVINGS WORKFLOW |
+-----------------------------------------------------------------------------------+
| [Step 1] Set Up Storage ==> Cash Envelope, Piggy Bank, or Digital e-Wallet |
| [Step 2] Automate Trigger ==> Link to Daily Commute or Morning Coffee Routine |
| [Step 3] Track Progress ==> Check off Printable Habit Chart or App |
| [Step 4] Monthly Deposit ==> Transfer Accumulated Cash to High-Yield Account |
| [Step 5] Review & Scale ==> Evaluate Balances & Increase Goals Gradually |
+-----------------------------------------------------------------------------------+
Step 1: Choose Your Savings Vessel
Select a dedicated container for your physical twenty-peso coins or bills. You can use an opaque piggy bank, a labeled cash envelope, or a clear acrylic savings box. If you prefer cashless digital payments, open a separate sub-account or digital “savings pocket” inside a Philippine e-wallet or digital banking app. Keeping these savings separate from your everyday spending cash prevents accidental impulse purchases.
Step 2: Establish a Daily Trigger
Tie your ₱20 savings action to an existing daily habit so you never forget. For instance, put ₱20 into your savings jar immediately after returning home from your commute, or set an automated daily alarm at 8:00 AM on your smartphone. When the trigger occurs, immediately set aside your twenty pesos before making any discretionary purchases for the day.
Step 3: Use a Visual Tracking Sheet
Visual progress keeps motivation high over 365 days. Print out a habit tracking calendar or draw a 365-box grid on a notepad. Every time you deposit your ₱20, shade in one box. Seeing your progress visibly grow reinforces the psychological reward loop, making it easier to stick to the challenge through busy work weeks.
Step 4: Transfer Funds to High-Yield Digital Accounts Monthly
To protect your cash from physical damage, loss, or inflation, transfer your collected monthly savings of ₱600 into a high-interest Philippine digital bank account at the end of every month. Modern digital banks regulated by the Bangko Sentral ng Pilipinas offer competitive annual interest rates, allowing your small daily contributions to earn compound interest over time.
Step 5: Review and Re-align Annually
At the end of twelve months, evaluate your accumulated balance of ₱7,300 plus earned interest. Decide whether to roll this capital into a dedicated emergency fund, an insurance policy, or low-risk investment instruments like Pag-IBIG MP2. Once you master the ₱20 baseline, you can choose to scale up to higher challenge amounts like ₱50 or ₱100 daily.
Benefits
Starting and maintaining the ₱20 Daily Savings Challenge delivers significant practical and psychological benefits for your personal finances:
- Builds Unshakable Consistency: Developing the daily habit of setting aside money trains your mind to prioritize saving over spending every single day.
- Low Entry Barrier: A twenty-peso daily commitment is affordable for students, entry-level workers, freelancers, and daily wage earners alike.
- Creates an Initial Safety Net: Saving ₱7,300 annually provides a basic financial cushion to handle sudden medical bills, appliance repairs, or unexpected travel needs.
- Reduces Financial Anxiety: Knowing you have cash accumulating every day gives you peace of mind and reduces stress during tough economic weeks.
- Eliminates Loose Coin Clutter: The challenge turns loose ₱20 coins and small bills sitting in your pockets or bags into a structured financial fund.
- Teaches Mindfulness in Daily Spending: Skipping a single small snack or jeepney convenience purchase to secure your daily ₱20 heightens your spending awareness.
- Harnesses the Power of Compound Interest: Moving your daily savings into regulated digital banks helps your money outpace inflation over time.
- Encourages Family Financial Literacy: Involving your children or siblings in shading habit trackers teaches young family members good money management skills early.
- Serves as a Gateway to Investing: Successfully completing this challenge builds the confidence needed to explore stock market trading, mutual funds, and Pag-IBIG MP2.
- Fosters Behavioral Resilience: Sticking to a target for 365 straight days builds mental discipline that extends into other productive life goals.
Costing and Budget Considerations
One of the best aspects of the ₱20 Daily Savings Challenge is its minimal upfront cost. You do not need expensive software or financial advisors to start.
- Daily Allocation: ₱20 per day = ₱140 per week = ₱600 per 30-day month = ₱7,300 per 365-day year.
- Physical Storage Tools: A basic piggy bank, plastic container, or cash envelope costs between ₱0 (reusing a clean jar) and ₱50 at local department stores.
- Printable Trackers: ₱0 if drawn by hand on paper, or around ₱10 to ₱20 for printouts at a neighborhood computer shop.
- Banking Fees: ₱0 when using regulated Philippine digital banks with free interbank fund transfers via InstaPay or PESONet.
- Opportunity Cost: The ₱20 daily outlay is equal to skipping half a cup of commercial coffee, one fast-food add-on, or a short tricycle ride that you could easily walk instead.
Pros and Cons
| Pros (Advantages) | Cons (Limitations) |
| Extremely easy to start with minimal capital | Takes a full year to accumulate ₱7,300 |
| Fits seamlessly into low-income household budgets | Cash kept at home risks physical theft or loss |
| Helps build daily financial discipline | Inflation can erode the value of physical cash |
| Flexible across physical cash and digital e-wallets | Does not replace a full 6-month emergency fund |
| Low psychological pressure compared to large monthly targets | Physical coins can become bulky over long periods |
| High completion rates among financial beginners | Easy to skip days without personal accountability |
| Combines easily with other budgeting methods | Requires manual effort if you choose cash over automation |
| Highly rewarding visual tracking process | May feel too small for high-income earners |
| Safe way to practice cash flow management | Digital transfers may involve minor tech hiccups |
| Prepares you for larger financial investments | Requires strict discipline to avoid spending the jar early |
Case Studies
Scenario 1: The University Student in Manila
Mark, a college student in Sampaloc, receives a daily allowance of ₱250. By walking short distances instead of taking a tricycle and packing water from home, he frees up ₱20 every afternoon. He drops the coin into a desk jar each night. After ten months, Mark saved ₱6,000, which covered his thesis printing costs and graduation fees without asking his parents for extra money.
Scenario 2: The BPO Shift Worker in Cebu
Sarah works night shifts at an IT park BPO. She regularly spent extra change on convenience store snacks during lunch breaks. She decided to start the ₱20 challenge by placing ₱20 into a digital savings vault as soon as her shift began. Over one year, Sarah accumulated ₱7,300 plus digital bank interest, funding her annual medical check-up and emergency prescription medicines.
Scenario 3: The Small Store Owner in Davao
Ate Rose runs a neighborhood sari-sari store. She routinely receives loose ₱20 coins from customers. She decided to put one ₱20 coin into a locked tin box at the end of every business day. By the end of December, she had saved ₱7,300, which she used to purchase extra fast-selling inventory for the holiday season without taking high-interest loans.
Scenario 4: The Freelance Graphic Designer
James earns an irregular income as a remote designer. During lean months, large savings goals overwhelmed him. He adopted the ₱20 challenge because the daily commitment was manageable regardless of client volume. Maintaining the habit gave him confidence, and he eventually scaled his savings to ₱100 a day when new client contracts arrived.
Scenario 5: The Commuter in Pasig
Ramon realized that buying bottled water during his daily bus ride cost him ₱25 every day. He switched to carrying a reusable water bottle and redirected ₱20 of his daily savings into his e-wallet account. At the end of 12 months, his accumulated savings funded a brand-new set of heavy-duty rainy season commuting gear.
Scenario 6: The Young Married Couple in Iloilo
Elena and her husband decided to run the ₱20 challenge together, each contributing ₱20 daily into a joint home savings box. Their combined daily ₱40 contribution yielded ₱14,600 in one year. They used this money as a partial down payment for a home appliance upgrade package during year-end sales.
Scenario 7: The Public School Teacher
Teacher Grace integrated the ₱20 savings challenge into her classroom as a practical math and life skills lesson. She saved ₱20 daily alongside her students in a classroom tracking jar. At the end of the school year, her personal savings covered classroom teaching supplies without dipping into her regular monthly salary.
Scenario 8: The Delivery Rider in Cavite
Dan works as a food delivery rider. He decided that his very first tip of every working day, usually around ₱20, would go directly into a separate coin pouch. Over eleven months, Dan amassed over ₱6,500, which funded complete routine maintenance, oil changes, and fresh tires for his motorcycle.
Scenario 9: The Minimum Wage Factory Worker
Lito earned minimum wage and felt that financial planning tools were not made for his salary level. The ₱20 challenge offered an approachable entry point. By setting aside ₱20 every morning before leaving for work, he built his very first ₱7,300 emergency fund, breaking a cycle of relying on informal neighborhood lenders.
Scenario 10: The Overseas Filipino Worker (OFW) Family
An OFW family in Pampanga wanted to manage their remittance money better. The spouse remaining in the Philippines started a daily ₱20 challenge for their two teenage children. The habit taught the children the value of money, and their combined annual savings of ₱14,600 funded a family emergency medical reserve.
Key Takeaways
- Small Habits Yield Real Results: Saving ₱20 daily builds an annual total of ₱7,300 without placing heavy pressure on your monthly wallet.
- Consistency Trumps Amount: The psychological habit of saving daily matters more than the actual amount when starting your financial journey.
- Keep Savings Separate: Storing your challenge funds away from your regular spending account prevents accidental impulse purchases.
- Leverage Digital Banking: Moving physical cash into regulated digital banks protects your principal and earns competitive annual interest rates.
- Use Visual Tracking: Shading in a physical habit tracker keeps you motivated across all 365 days of the year.
- Tie Actions to Triggers: Linking your daily savings to an existing routine, like your morning commute, ensures you never forget to deposit your money.
- Protect Against Inflation: Once your daily savings accumulate, transfer them into high-yielding tools to maintain your purchasing power.
- Small Sacrifices Add Up: Eliminating a single minor daily expense easily frees up the twenty pesos needed for the challenge.
- Builds a Financial Gateway: Successfully saving ₱7,300 builds the mental discipline required for advanced investing and wealth-building strategies.
- Anyone Can Participate: Students, daily wage earners, BPO employees, and store owners can all execute this challenge successfully.
Frequently Asked Questions
1. Is ₱20 a day really enough to make a difference in the Philippines?
Yes. Saving ₱20 daily yields ₱7,300 over a year. For many Filipino households, ₱7,300 covers several weeks of grocery bills, unexpected medical prescriptions, or urgent utility payments during emergencies.
2. Should I save physical ₱20 coins or use digital money?
Both methods work well. Physical coins or bills provide a tactile experience that works great for visual learners. Digital e-wallets and banking apps offer better security, interest earnings, and convenience.
3. What should I do if I forget or miss a day?
Do not get discouraged or quit the challenge. Simply deposit ₱40 the following day to catch up, shade in your missed box on your tracking chart, and continue your routine as normal.
4. Where is the safest place to deposit my accumulated ₱20 savings?
The safest place is a Bangko Sentral ng Pilipinas (BSP)-regulated bank or digital bank. Deposits in these banks are insured by the Philippine Deposit Insurance Corporation (PDIC) up to ₱500,000 per depositor.
5. Can I increase my daily savings amount during the challenge?
Absolutely. The ₱20 challenge serves as a baseline habit. If your budget permits, you can scale up to ₱50, ₱100, or flexible amounts depending on your daily cash flow.
6. How do I prevent myself from spending the savings jar early?
Use an opaque or sealed piggy bank that requires physical effort to open, or store your savings in a separate digital bank account without ordering a physical debit card.
7. Is the ₱20 daily savings challenge suitable for students?
Yes. The low daily requirement makes it ideal for high school and college students who want to build smart financial habits using their daily school allowances.
8. How much interest can my ₱7,300 earn in a digital bank?
Digital banks in the Philippines often offer competitive interest rates ranging from 2.5% to 6% per annum. Depositing your funds monthly yields higher returns than keeping cash in a traditional jar at home.
9. What should I do with the money once the year ends?
Use your accumulated ₱7,300 as the foundation of your emergency fund, pay off high-interest personal debts, or invest it into government-backed programs like Pag-IBIG MP2.
10. How does this challenge compare to the 52-Week Savings Challenge?
The ₱20 daily challenge keeps your deposit amount constant every single day. The 52-week challenge increases the deposit amount every week, which can become difficult during late-year holiday seasons.
Conclusion
The journey to lasting financial wellness does not require a massive salary or complex financial strategies. It begins with the decision to take control of the small daily choices within your power. The ₱20 Daily Savings Challenge proves that consistency, discipline, and clear goals can turn loose change into a meaningful financial safety net. 💡
By setting aside just twenty pesos today, setting up a visual tracker, and moving your savings into high-yielding digital accounts, you lay the groundwork for long-term financial independence. Do not wait for the “perfect” time or a salary raise to start saving money. Take out a ₱20 coin, place it in a jar or digital account right now, and watch your financial confidence grow one day at a time.
Link Resources
- Bangko Sentral ng Pilipinas (BSP) Financial Inclusion
- Philippine Deposit Insurance Corporation (PDIC)
- Pag-IBIG Fund Official Website
- National Economic and Development Authority (NEDA)
- Department of Trade and Industry (DTI) Consumer Care
Key Phrases
- 20 peso daily savings challenge guide
- how to save money daily in the Philippines
- building an emergency fund with small change
- micro savings habits for Filipino workers
- high yield digital bank savings Philippines
- step by step money saving challenge guide
- practical budgeting tips for low income
- daily financial habits for college students
- smart money management tips Philippines
- converting daily loose coins into real savings
Best Hashtags
#SavingsChallengePH #IpongPiso #FinancialLiteracyPH #BudgetingTipsPH #PisoChallenge #SmartInvestingPH #DigitalBankingPH #EmergencyFundPH #PersonalFinancePH #IponGoals2026
Disclaimer
The information is for educational purposes only and subject to change, and it is highly recommended to consult local authorities for the latest and most accurate updates. We do not constitute endorsement of any specific technologies or methodologies or endorse of any specific products or services. For queries, questions, corrections, or updates, please send us a message through our Contact Us page. We welcome feedback to ensure our guides remain accurate, updated, and helpful for everyone